The review of where business is established, licensed and banked. Subscribe
Jurisdicta
The review of where business is established, licensed and banked.
Issue 003Sunday 1 November 2026
Issue 003 · Sunday 1 November 2026

Who owns this company? The disclosure rules arriving in Mauritius and the Seychelles

Both Indian Ocean centres legislated this year to record more about the people behind companies, partnerships and trusts. The first deadline falls on 31 December.

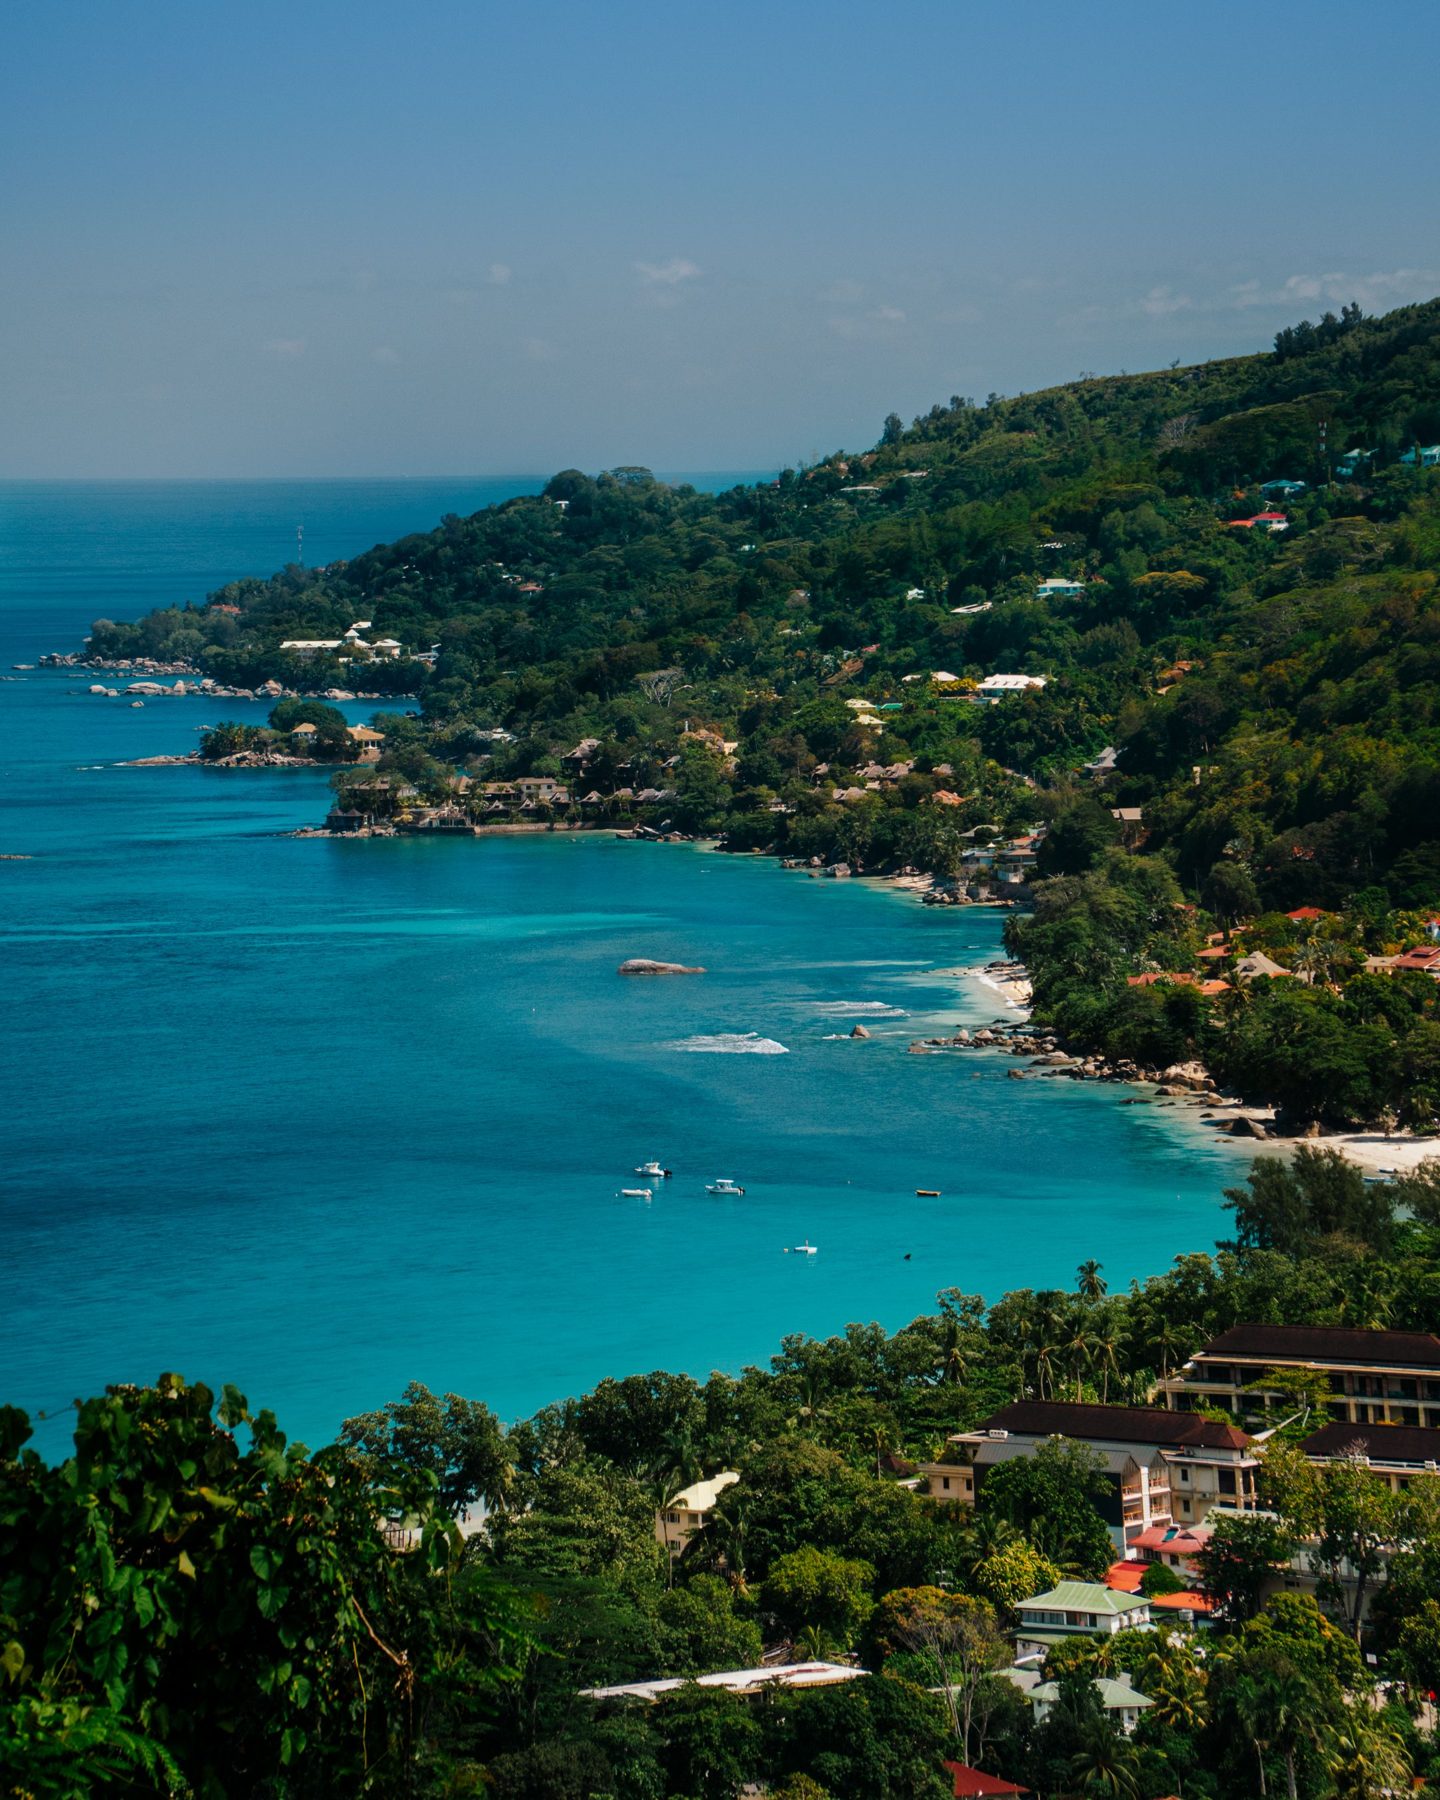
Beau Vallon beach, Mahé, Seychelles
Photo: Matteo Parisi / Pexels

01

Cover story

Mauritius · Seychelles

In August, within days of each other, the parliaments of Mauritius and the Seychelles passed laws that change what the registers must hold about the people behind entities registered there. Taken one at a time, neither change is dramatic. Read together, they close a period in which the identity of a nominee director's principal, or a beneficial owner's date of birth, could simply be left off the record.

Both countries face mutual evaluations by ESAAMLG, the regional body of the FATF network, over the next two years. The Seychelles does not hide the connection: the explanatory memorandum to its amending bill cites FATF Recommendation 24, on the transparency of legal persons.

Read the cover story

02

The Economy

Singapore · Hong Kong · United Arab Emirates · British Virgin Islands · Mauritius · Seychelles

Where foreign investment went in 2025: six hubs compared

Singapore pulled further ahead, Hong Kong fell back and the UAE's inflows rose again. UNCTAD's latest figures put the hubs we cover side by side.

FDI inflows, 2025 (USD billion)

Read The Economy

03

The Rulebook

5 items

RAKEZ: police clearance now required for ten more nationalities

Since 20 July 2026, RAKEZ has required a Good Conduct Certificate from new employment and investor visa applicants from Ghana, Lebanon, Lithuania, Morocco, Mozambique, Pakistan, Senegal, Syria, Tonga and Zambia. The change follows an update from the federal identity and customs authority.

What to do: RAKEZ companies and founders should build the certificate and its embassy attestation into hiring and shareholder timelines for applicants from the twenty-four listed countries, and have it in hand before the visa application is filed.

Our readingPlan start dates on the basis that visas for affected founders and staff will take longer. The change comes from a federal update, so firms elsewhere in the UAE should check whether the same list applies to them.

Read the full article · 3 min →

FSC launches a Register of Trusts: existing trusts must be loaded by 15 January 2027

On 30 September 2026 the Financial Services Commission (FSC) launched a Register of Trusts, which is not open to the public. Qualified Trustees must load basic and beneficial ownership information for every trust they administer by 15 January 2027, and must report any change within five working days.

What to do: Qualified Trustees should register for the portal now and plan to load every trust they administer, foreign trusts included, by 15 January 2027, with a process in place for reporting changes within five working days.

Our readingAnother piece of the trust transparency framework, and one that assessors at the next mutual evaluation are likely to test. The deadline is the easier half; the harder work is the quality of the data.

Read the full article · 4 min →

Hong Kong annual returns can now be filed with iAM Smart+ without an e-filing account

Since 17 August 2026, the Companies Registry has accepted a company's annual return (Form NAR1) and notice of change of registered office (Form NR1) from holders of iAM Smart+, the government's digital identity, without their first registering for e-filing.

What to do: If a director or the company secretary of your Hong Kong company holds iAM Smart+, consider using the new route for the next annual return, and diarise the 42-day filing window that follows the incorporation anniversary.

Our readingA small change, and a characteristic one, in keeping with Hong Kong's effort to keep company administration quick. The Hong Kong Identity Card requirement narrows its reach, so most subsidiaries run from overseas will go on filing through their company secretary.

Read the full article · 4 min →

European Union

Panama and Viet Nam leave the EU tax blacklist; eight jurisdictions remain

On 9 October 2026 the Council of the EU removed Panama and Viet Nam from Annex I, its list of non-cooperative jurisdictions for tax purposes, and moved both to Annex II. Annex I now names eight jurisdictions, American Samoa, Anguilla, Guam, Palau, Russia, the Turks and Caicos Islands, the US Virgin Islands and Vanuatu.

What to do: Before the next revision in February 2027, update counterparty, payment and intermediary risk policies that refer to the EU list, and check with EU group companies how and when their national defensive measures cease to apply to Panama and Viet Nam.

Our readingNone of the main hubs we cover is on Annex I, but the British Virgin Islands remains on Annex II, so BVI structures stay under watch. For Panama and Viet Nam the move is conditional: Annex II is a waiting room, and a jurisdiction can be sent back.

Read the full article · 4 min →

FATF

FATF removes Bulgaria, Monaco, Côte d'Ivoire and the DRC from the grey list; Vietnam stays

At its plenary ending on 30 October 2026, the Financial Action Task Force (FATF) removed Bulgaria, Monaco, Côte d'Ivoire and the Democratic Republic of the Congo from its list of jurisdictions under increased monitoring, and added none. Vietnam stays on the list, and the FATF has said it will consider next steps if progress is not made before the next plenary. The list of high-risk jurisdictions subject to a call for action is unchanged, with Iran and Myanmar named in press reports of the outcome.

What to do: Once you have read the FATF's own statements, update the counterparty, onboarding and correspondent-banking risk lists that refer to the FATF grey list, and check whether your bank applies the change at once or with a lag.

Our readingThe UAE is on neither list, and nor are the other hubs we cover, so the practical effect is on counterparties. For clients with links to Vietnam, enhanced due diligence stays in place, and on the press accounts the FATF has signalled a harder line by the next plenary.

Read the full article · 2 min →

04

The Structure

Illustrative

Who appears on which register: a UAE company held through a Seychelles IBC and a Mauritius foundation

A layered ownership chain, walked from the founder down, and what each layer now records about the people behind it.

Founder100%Director100%FounderNon-resident of MauritiusMAURITIUSFoundationHolds the sharesNominee directorAppointed by the founderSEYCHELLESHolding companyInternational Business CompanyUAEOperating companyLicensed company
Illustrative structure. Not a client engagement and not advice for any particular case.

Why each piece sits where it does

05

Immigration by Investment

2 features
06

Wealth and Succession

1 feature

DIFC Courts probate: from death certificate to grant

A registered will settles who inherits, but it does not move a single asset. For a non-Muslim family relying on a will held by the DIFC Courts, that happens only once the executor has obtained a Probate Order and, for most Dubai assets, had it executed through the Dubai Courts. This piece follows the officially published process, with what it costs and where it tends to stall.

Read the feature · 5 min →

07

Field Notes

On the ground

Mutual evaluations: the dates do not agree

The ESAAMLG calendar gives possible dates for the next mutual evaluations of both Indian Ocean centres. The Seychelles goes first: an onsite visit in June or July 2027, then a plenary discussion in March or April 2028. Mauritius follows, with an onsite visit in January or February 2028 and a plenary in August or September 2028.

The Mauritius Budget Speech 2026-2027 talks of "full readiness for the 2027 Mutual Evaluation". The calendar says 2028. That matters less than it looks. Assessors judge how the rules work in practice over the period before the visit, so the year before the onsite is the year the evidence gets made.

On the ground, expect more questions in 2027 from administrators, banks and registered agents: who owns this, where the money came from, what each entity is for. The legislation passed this year is the script they will work from.

08

By the Numbers

8
Jurisdictions on the EU list of non-cooperative tax jurisdictions after 9 October 2026
American Samoa, Anguilla, Guam, Palau, Russia, the Turks and Caicos Islands, the US Virgin Islands and Vanuatu. Panama and Viet Nam left in October, for Annex II. None of the main hubs we cover is listed.
09

Jurisdiction Profile

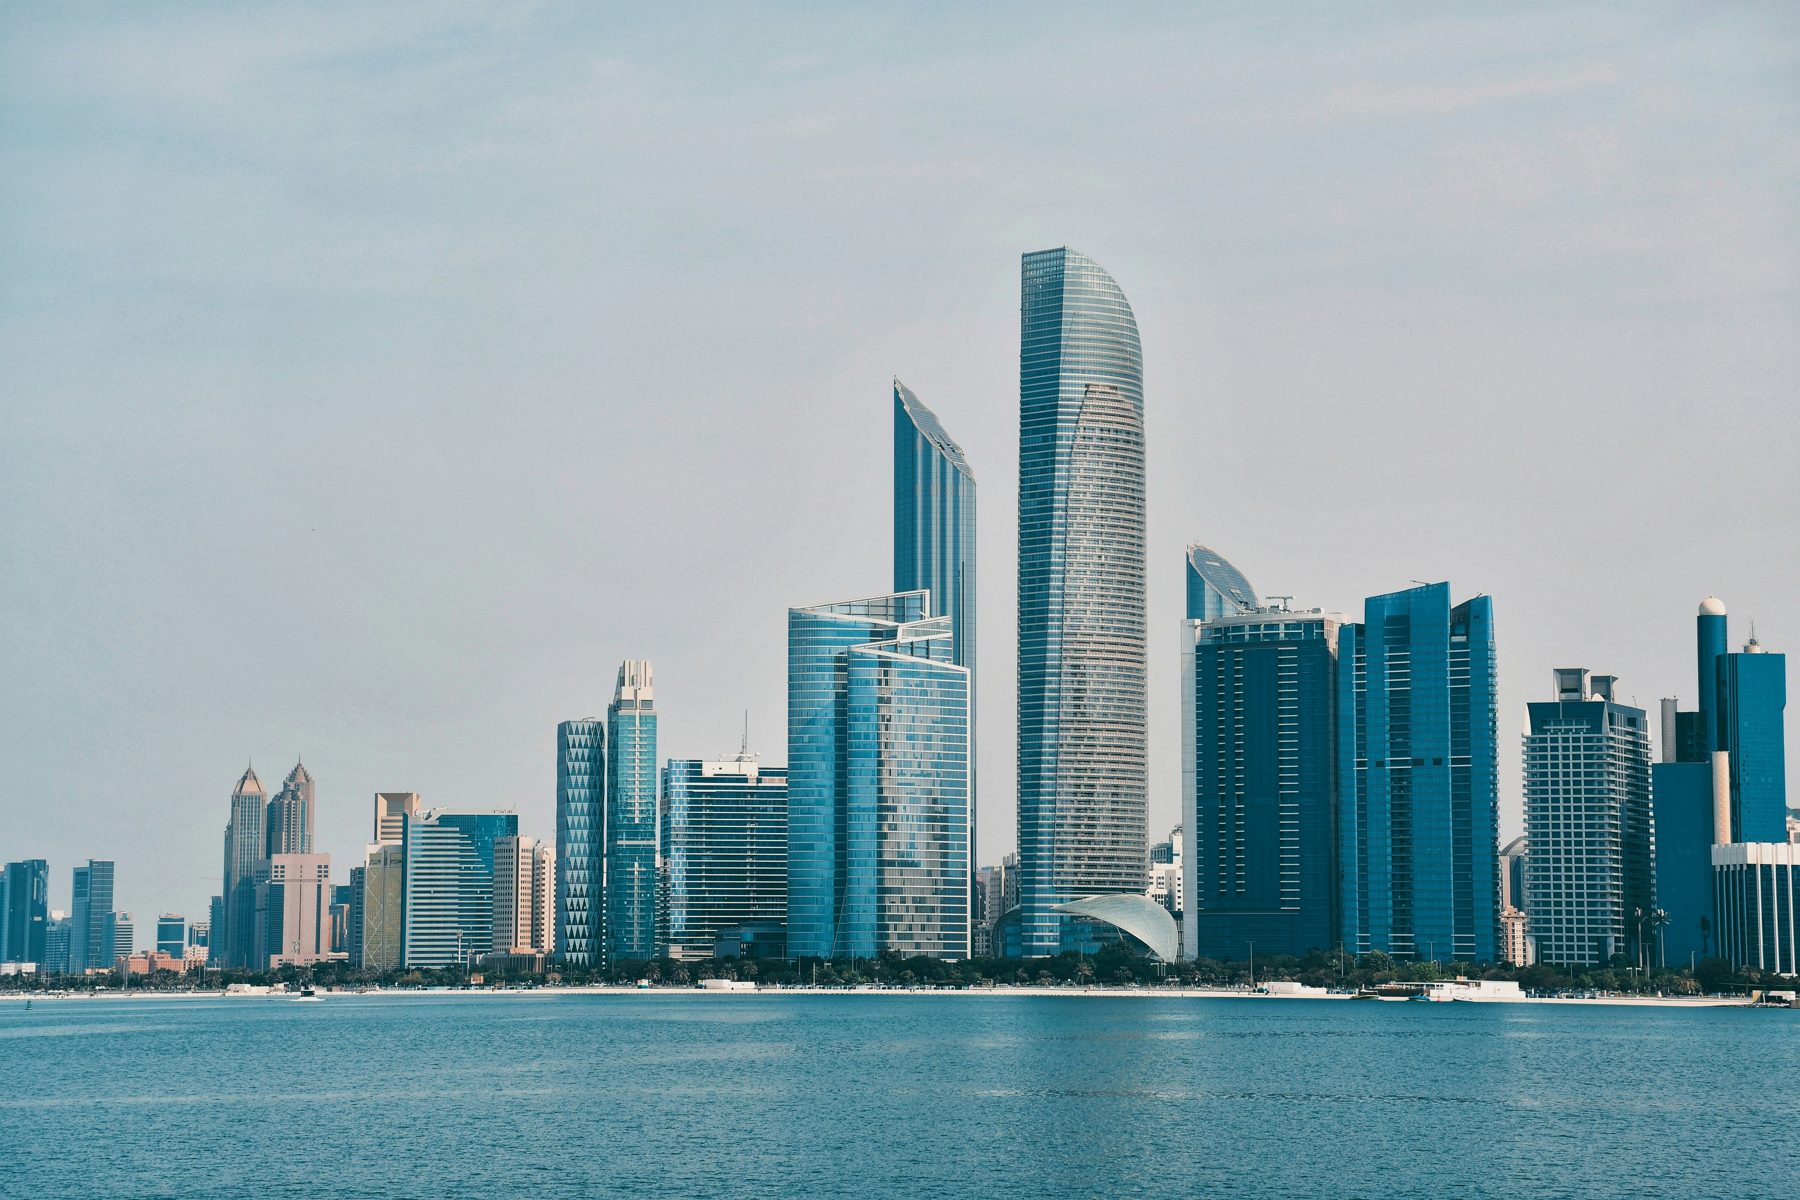
Abu Dhabi skyline seen from Corniche Beach
Photo: Karthik B K / Unsplash
United Arab Emirates

The United Arab Emirates: low tax, now with a rulebook

What it is used for. Regional headquarters, trading and service companies, family offices, funds and, more and more, regulated financial and virtual asset businesses. Mainland companies sell into the domestic market. Free zone companies serve international clients and, where their licence allows, the region.

The regulators. At federal level, the Ministry of Finance and the Federal Tax Authority handle tax, the Central Bank handles banking and payments, and the Capital Market Authority handles securities. The DIFC and ADGM each have their own financial regulator, the DFSA and the FSRA respectively, and their own common law courts. In Dubai outside the DIFC, VARA regulates virtual assets.

Tax. Corporate tax is 9 per cent on taxable income above AED 375,000. A Qualifying Free Zone Person can pay 0 per cent on qualifying income if it meets the conditions. Withholding tax is 0 per cent. VAT has applied at 5 per cent since 1 January 2018. For financial years starting on or after 1 January 2025, a Domestic Minimum Top-up Tax lifts large multinational groups, those with revenue of EUR 750 million or more, to a 15 per cent effective rate. Low tax, then, with conditions attached.

Treaties. The UAE has concluded 137 double taxation agreements, on the Ministry of Finance's count.

Transparency. Legal persons keep a register of real beneficiaries at a 25 per cent threshold and file it with their registrar under Cabinet Resolution No. 109 of 2023. The FATF took the UAE off its list of jurisdictions under increased monitoring in February 2024.

Currency. The dirham is pegged to the US dollar at AED 3.6725.

What to watch. E-invoicing for businesses with revenue of AED 50 million or more, from 1 January 2027; the end of the one-year period to align with the Capital Market Authority law; new Central Bank rules on operational risk and on SME customer protection; and tighter VARA requirements on client reserve assets.
Our readingStill the strongest all-round base in the region for an operating business. The tax advantage has narrowed and the compliance load has grown. Price both into the plan.

Everything we have published on United Arab Emirates →

10

Further reading

11

The Diary

Next 90 days
DateJurisdictionWhat falls dueWho it affectsStatus
6 November 2026 ADGM Consultations close on the FSRA fees and general rulebook revisions (CP 6/2026) and a framework for business centres (CP 7/2026) ADGM firms and business-centre operators wishing to comment Confirmed
16 November 2026 United Arab Emirates Excise tax return and payment due Excise tax registrants Confirmed
16 November 2026 Hong Kong Profits tax returns for 2025/26 due, accounting date code M (year ends 1 January to 31 March 2026), under the block extension scheme Companies filing through tax representatives Confirmed
30 November 2026 Singapore Form C-S, Form C-S (Lite) and Form C due for Year of Assessment 2026 Companies tax resident or operating in Singapore Confirmed
30 November 2026 Mauritius Corporate tax return and tax due for years ended May 2026; advance payment statement for the quarter to 31 August 2026 Companies, including Global Business Companies Confirmed
30 November 2026 United Arab Emirates Corporate tax return and payment due for tax periods ended 28 February 2026 (nine months after the period end) Corporate tax registrants with a February year end Confirmed
30 November 2026 ADGM Consultation closes on FSRA guidance on DeFi risk management (CP 5/2026) Virtual asset and DeFi firms in or entering ADGM Confirmed
30 November 2026 United Arab Emirates Top-up Tax registration deadline for in-scope entities whose fiscal year ended before 30 April 2026 (FTA Decision No. 12 of 2026, Art. 2(2)); AED 10,000 penalty for late registration UAE entities of multinational groups with EUR 750 million or more in revenue, or their Domestic Designated Filing Entity Confirmed
29 December 2026 Mauritius Corporate tax return and tax due for years ended June 2026; advance payment statement for the quarter to 30 September 2026 Companies, including Global Business Companies Confirmed
31 December 2026 Seychelles Register of directors must record the nominee status of any director and the nominator's details International Business Companies Confirmed
31 December 2026 Mauritius Audited financial statements due to the FSC for licensees with a June 2026 year end (six months after the year end) Global Business Companies and other FSC licensees Confirmed
31 December 2026 United Arab Emirates Corporate tax return and payment due for tax periods ended 31 March 2026 Corporate tax registrants with a March year end Confirmed
1 January 2027 United Arab Emirates E-invoicing becomes mandatory for businesses with annual revenue of AED 50 million or more VAT and corporate taxpayers above the threshold Confirmed
1 January 2027 Seychelles Filings must carry the names and appointment dates of a company's current directors International Business Companies and their registered agents Confirmed
1 January 2027 Singapore Crypto-Asset Reporting Framework regulations enter into force; reporting service providers begin collecting data Crypto-asset service providers with a Singapore nexus Confirmed
1 January 2027 DIFC Revised conflict-of-interest rules for credit rating agencies apply DFSA-authorised credit rating agencies Confirmed
1 January 2027 United Arab Emirates One-year period for firms to bring their status into line with the new Capital Market Authority law ends, unless extended by the CMA Board Firms carrying on financial or virtual asset activities within the CMA's scope To confirm
15 January 2027 Mauritius Initial population of the FSC Register of Trusts must be complete Qualified Trustees and management companies administering trusts Confirmed
15 January 2027 Mauritius Nil and loss returns due for years ended June 2026 Companies with no chargeable income for the year Confirmed

The full calendar →

Subscribe

Every issue, in your inbox

Every two weeks: the contents of the issue and the opening of the cover story, with a link to read it in full. Free. Unsubscribe in one click.