The review of where business is established, licensed and banked. Subscribe
Jurisdicta
The review of where business is established, licensed and banked.
Issue 002Sunday 18 October 2026
Issue 002 · Sunday 18 October 2026

The crypto transparency clock: what 1 January 2027 means for crypto businesses in the hubs we cover

Tax authorities are about to exchange information on crypto-asset users much as they already exchange bank account data. For most of the hubs we cover, collecting that data starts in seven weeks.

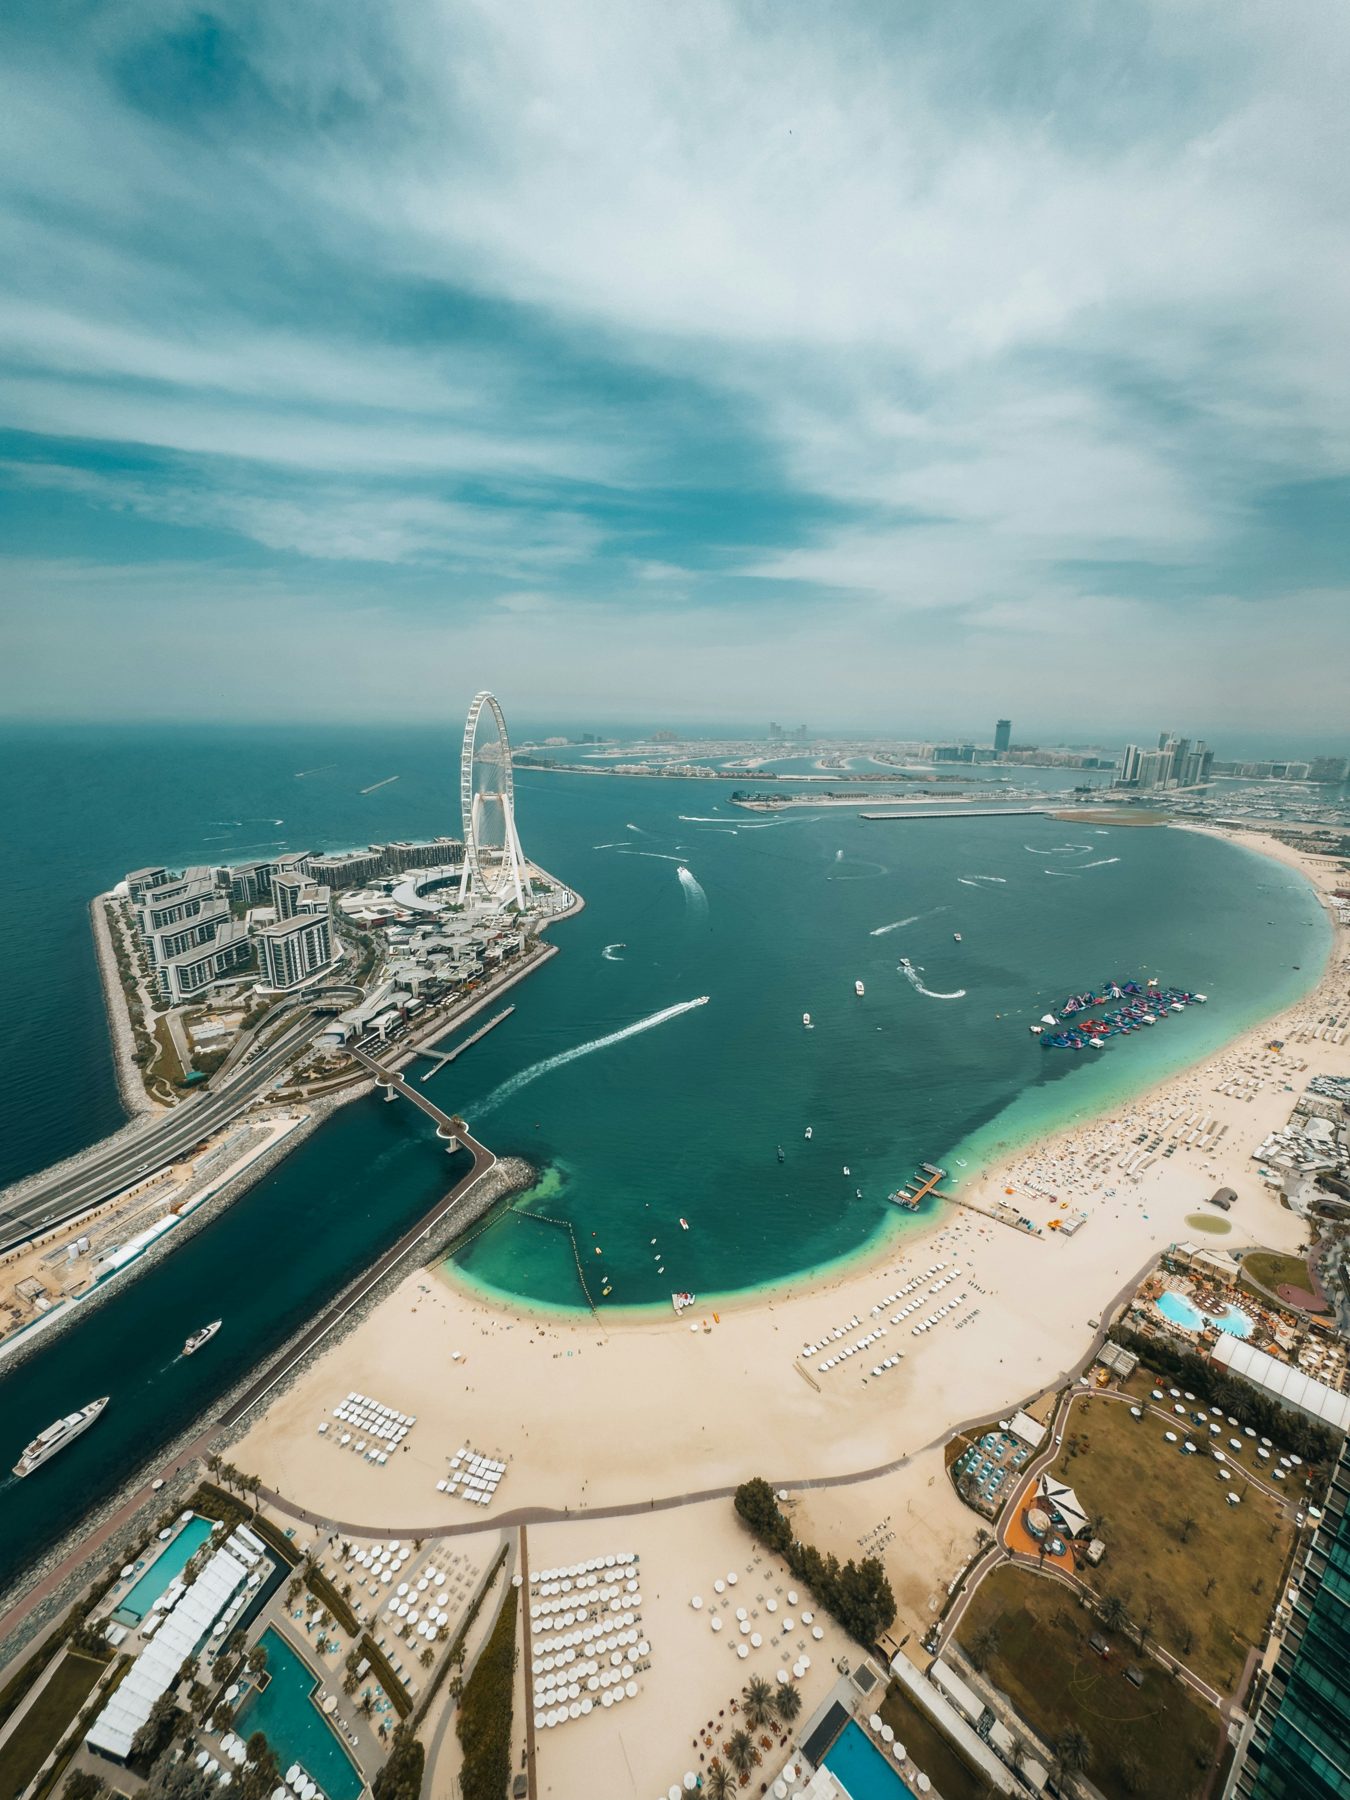
Aerial view of the Dubai coastline and buildings
Photo: Nejc Soklič / Unsplash

01

Cover story

United Arab Emirates · Singapore · Hong Kong · Seychelles · British Virgin Islands · Cayman Islands

The OECD's Crypto-Asset Reporting Framework (CARF) does for crypto what the Common Reporting Standard did for bank accounts. A crypto-asset service provider collects tax residence information from its users and reports those users, and their transactions, to its local tax authority. That authority then passes the information to the authorities where the users are resident.

Whether CARF reaches a crypto business is settled. When it arrives, and where, is the part still worth reading closely.

Read the cover story

02

The Economy

Mauritius

Mauritius: steady growth, with financial services doing more of the work

Statistics Mauritius has revised its estimate of real GDP growth in 2025 up to 3.5 per cent and expects 3.0 per cent this year. Financial services is the largest single contributor to the forecast.

Share of gross value added by sector, Mauritius, 2025

Read The Economy

03

The Rulebook

7 items

Capital Market Authority: the one-year window to adjust status closes at the end of 2026

If you fall within the scope of Decree-Law No. 33, you have one year to adjust your status to its provisions (Article 83). Federal Decree-Laws No. 32 and 33 of 2025 renamed the Securities and Commodities Authority as the Capital Market Authority and took effect on 1 January 2026. The CMA Board may extend the one-year period.

What to do: If you carry on any Article 3 Financial Activity in or into the UAE, outside the DIFC and ADGM, map your activities against the licence you hold and file or restructure before the period ends with 2026, unless the CMA Board announces an extension.

Our readingThe federal perimeter is closing. For activities offered onshore, a free zone address does not settle the question, and the virtual asset provisions in Article 39 deserve a close read.

Read the full article · 4 min →

VARA sets out what an audit of client reserve assets must cover

A VARA circular dated 6 October 2026 fixes the scope of the independent audit of reserve assets held for clients, which covers wallets, segregation, daily reconciliation and rehypothecation. It also restates the base rule. Virtual asset service providers must maintain reserve assets equal to 100 per cent of their liabilities to clients in respect of virtual asset activities.

What to do: If you are VARA-licensed and hold client virtual assets, send the circular to your auditor now and agree an audit plan that covers all seven scope areas before the next reserve audit begins.

Our readingRegulators usually look first at client asset protection after a market failure. VARA is setting the standard before one, and its emphasis on period coverage and unverifiable items will raise the bar for audit evidence.

Read the full article · 4 min →

New Central Bank operational risk regulation in force

The Operational Risk Management Regulation (Circular C 1/2026) has applied since 14 September 2026, replacing the 2018 regime. It covers every licensed financial institution that is a legal entity.

What to do: Central Bank licensees should complete and document a gap analysis against Circular C 1/2026 now. Start with incident notification procedures, the location of the Master System of Record and any planned outsourcing or system changes.

Our readingExpect operational risk and resilience to come up at the next supervisory visit. The prior approval steps in Articles 12 and 13 will add time to technology projects.

Read the full article · 4 min →

DFSA folds prudential forms into B110 and revises credit rating agency rules

From 2 October 2026, every authorised firm files prudential returns on a redesigned form B110, which the DFSA has created by merging forms B180 and B120 following Consultation Paper 174. Separately, more principles-based conflict of interest rules for credit rating agencies apply from 1 January 2027.

What to do: Authorised firms should check that their next prudential return is prepared on the redesigned form B110. Credit rating agencies should review their conflicts policies before 1 January 2027.

Our readingHousekeeping, but welcome. The DFSA is cutting reporting load where it sees duplication, and has left the more consequential token proposals from the same paper for later.

Read the full article · 3 min →

Minimum tax: investment funds excluded, filing date clarified, late-payment penalty halved

The Finance Act 2026 (Act No. 14 of 2026) amends the Qualified Domestic Minimum Top-up Tax provisions of the Income Tax Act. On the text as published, an investment fund that is an ultimate parent entity is now excluded, as is a real estate investment vehicle in the same position. Returns fall due 15 months from the end of the month in which the fiscal year ends, and the penalty for non-payment, previously 5 per cent, falls to 2.5 per cent.

What to do: Designated filers in groups with revenue of EUR 750 million or more should diarise the 15-month return date for each fiscal year, counted from the end of the month in which that year ends, and check whether any fund at the top of the group is now an excluded person.

Our readingOn the text as published, Mauritius is keeping its minimum tax aligned with the OECD rules while easing friction for funds, which matter more to it than to most jurisdictions.

Read the full article · 4 min →

MAS consults on legislation for its stablecoin framework

On 1 September 2026 the Monetary Authority of Singapore (MAS) opened a consultation on amendments to the Payment Services Act 2019 that would give legislative effect to its stablecoin regulatory framework, which covers stablecoins pegged to the Singapore dollar or to a G10 currency. Comments closed on 16 October 2026.

What to do: Issuers and platforms planning Singapore-regulated stablecoin activity should read the draft amendments now and map their product against the proposals on labelling, interest and redemption, so that they are ready when MAS publishes its response and the bill.

Our readingSingapore, the UAE and Hong Kong are each building a stablecoin regime. In Singapore's proposals, the joint issuance and recognition routes are the parts most likely to decide whether an issuer based elsewhere can reach Singapore users without relocating.

Read the full article · 4 min →

Companies House identity checks: the transition for existing companies is ending

Companies House began identity verification on 18 November 2025, with a 12-month transition period for existing companies. Within that period an existing director verifies when the company files its next annual confirmation statement, while an existing person with significant control must verify within 12 months of 18 November 2025.

What to do: Before 18 November 2026, and in any case before your next confirmation statement, check that every director and individual PSC of each UK subsidiary has verified and that the company holds their personal codes.

Our readingUK subsidiaries of Gulf and Indian Ocean groups are often run at a distance, with the filings left to an agent. The most likely way these groups will meet the new regime is a confirmation statement that fails because one director abroad has no code.

Read the full article · 4 min →

04

The Structure

Illustrative

A virtual asset group across Dubai, the Seychelles and the BVI

A familiar shape for crypto businesses, and the reason the holding company at the top has become its weakest link.

100%100%100%BankedFoundersShareholdersBVIHolding companyBVI business companyUAELicensed operating companyVARA licence (Dubai)SEYCHELLESInternational platformVASP licence requiredUAEOperating bank accountCorporate account
Illustrative structure. Not a client engagement and not advice for any particular case.

Why each piece sits where it does

05

Immigration by Investment

2 features
06

Field Notes

On the ground

Seychelles: check the register, not the certificate

On 16 October 2026 the Seychelles Financial Services Authority published a warning about a forged virtual asset service provider licence. It came after several warnings in September and October about entities carrying on activity without authorisation.

If you deal with a Seychelles crypto counterparty, the lesson is short. The licence document proves nothing. The FSA's own website is the record of who is licensed, and of which applications are still under assessment. Check it, every time.

The FSA has also reminded International Business Companies, in Circular No. 5 of 2026, that incorporation is not a licence. Those carrying on regulated activity abroad must say in their client documents and marketing which authority licenses them. On the ground, a Seychelles counterparty that cannot point to its licence on the FSA's site is either unlicensed or not what it says it is.

07

By the Numbers

USD 804m
Foreign direct investment into Mauritius in 2025
FDI into Mauritius rose 18 per cent in 2025. In the Seychelles it nearly doubled, from a smaller base. Both figures measure investment into the domestic economy. They do not capture flows routed through global business companies.
08

Jurisdiction Profile

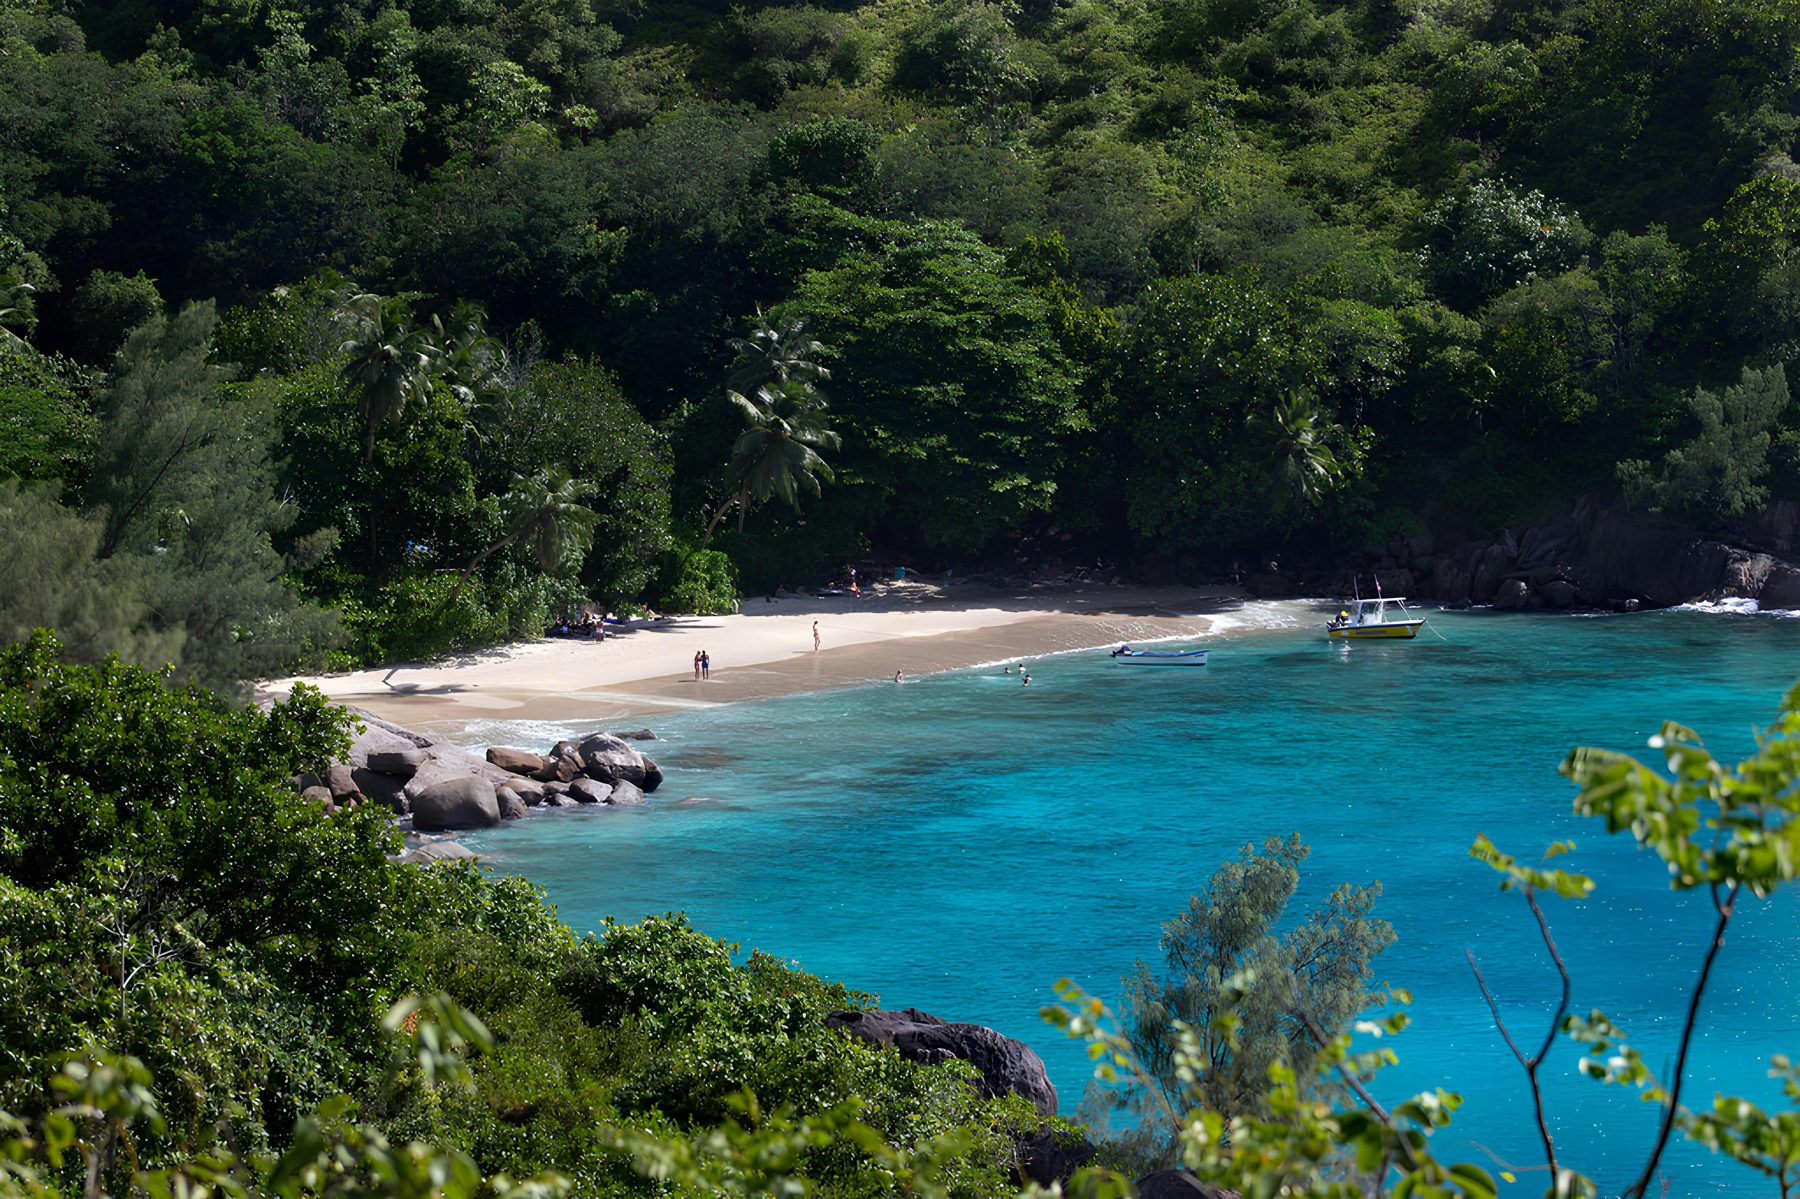
Anse Major beach, Mahé, Seychelles
Photo: seytales / Unsplash
Seychelles

Seychelles: from registry to regulated centre

What it is used for. International Business Companies for holding, trading and investment and, more and more, licensed businesses in securities, funds, insurance and virtual assets.

The regulator. The Financial Services Authority (FSA) regulates non-bank financial services, among them fiduciary services, capital markets, collective investment schemes and insurance. The same body registers International Business Companies, foundations, limited partnerships and trusts.

The main vehicles. First, the International Business Company under the International Business Companies Act 2016. Then foundations under the Foundations Act 2009, trusts under the Trusts Act 2021, protected cell companies and limited partnerships.

Incorporation. Through a Seychelles-licensed International Corporate Service Provider, which then acts as the company's registered agent.

What it costs. The FSA's published schedule sets an IBC registration fee of USD 130 and an annual fee of USD 140, due by each anniversary of incorporation. Pay late and penalties follow.

Tax. Under the Business Tax Act as amended in 2021, a resident company's foreign passive income is treated as Seychelles-source unless the company is a qualifying company with adequate economic substance in the tax year.

Licences. A securities dealer needs minimum paid-up capital of USD 50,000; an investment adviser needs USD 25,000. Any virtual asset business incorporated or registered in the Seychelles needs a licence under the VASP Act 2024.

Transparency. A beneficial owner is any natural person who owns or controls 10 per cent or more of a legal person. IBCs have until 31 December 2026 to record the nominee status of their directors and who nominated them, and from 1 January 2027 their filings must carry the names and appointment dates of current directors.

Standing. In January 2026 the Global Forum rated the Seychelles Largely Compliant on exchange of information on request, and in February 2026 the EU removed it from Annex II of its tax list. Its next ESAAMLG mutual evaluation is scheduled for 2027 to 2028.
Our readingStill the lowest-cost credible IBC jurisdiction we cover, and stricter every year. Choose it for simplicity. Do not choose it for secrecy.

Everything we have published on Seychelles →

09

The Diary

Next 90 days
DateJurisdictionWhat falls dueWho it affectsStatus
6 November 2026 ADGM Consultations close on the FSRA fees and general rulebook revisions (CP 6/2026) and a framework for business centres (CP 7/2026) ADGM firms and business-centre operators wishing to comment Confirmed
16 November 2026 United Arab Emirates Excise tax return and payment due Excise tax registrants Confirmed
16 November 2026 Hong Kong Profits tax returns for 2025/26 due, accounting date code M (year ends 1 January to 31 March 2026), under the block extension scheme Companies filing through tax representatives Confirmed
30 November 2026 Singapore Form C-S, Form C-S (Lite) and Form C due for Year of Assessment 2026 Companies tax resident or operating in Singapore Confirmed
30 November 2026 Mauritius Corporate tax return and tax due for years ended May 2026; advance payment statement for the quarter to 31 August 2026 Companies, including Global Business Companies Confirmed
30 November 2026 United Arab Emirates Corporate tax return and payment due for tax periods ended 28 February 2026 (nine months after the period end) Corporate tax registrants with a February year end Confirmed
30 November 2026 ADGM Consultation closes on FSRA guidance on DeFi risk management (CP 5/2026) Virtual asset and DeFi firms in or entering ADGM Confirmed
30 November 2026 United Arab Emirates Top-up Tax registration deadline for in-scope entities whose fiscal year ended before 30 April 2026 (FTA Decision No. 12 of 2026, Art. 2(2)); AED 10,000 penalty for late registration UAE entities of multinational groups with EUR 750 million or more in revenue, or their Domestic Designated Filing Entity Confirmed
29 December 2026 Mauritius Corporate tax return and tax due for years ended June 2026; advance payment statement for the quarter to 30 September 2026 Companies, including Global Business Companies Confirmed
31 December 2026 Seychelles Register of directors must record the nominee status of any director and the nominator's details International Business Companies Confirmed
31 December 2026 Mauritius Audited financial statements due to the FSC for licensees with a June 2026 year end (six months after the year end) Global Business Companies and other FSC licensees Confirmed
31 December 2026 United Arab Emirates Corporate tax return and payment due for tax periods ended 31 March 2026 Corporate tax registrants with a March year end Confirmed
1 January 2027 United Arab Emirates E-invoicing becomes mandatory for businesses with annual revenue of AED 50 million or more VAT and corporate taxpayers above the threshold Confirmed
1 January 2027 Seychelles Filings must carry the names and appointment dates of a company's current directors International Business Companies and their registered agents Confirmed
1 January 2027 Singapore Crypto-Asset Reporting Framework regulations enter into force; reporting service providers begin collecting data Crypto-asset service providers with a Singapore nexus Confirmed
1 January 2027 DIFC Revised conflict-of-interest rules for credit rating agencies apply DFSA-authorised credit rating agencies Confirmed
1 January 2027 United Arab Emirates One-year period for firms to bring their status into line with the new Capital Market Authority law ends, unless extended by the CMA Board Firms carrying on financial or virtual asset activities within the CMA's scope To confirm
15 January 2027 Mauritius Initial population of the FSC Register of Trusts must be complete Qualified Trustees and management companies administering trusts Confirmed
15 January 2027 Mauritius Nil and loss returns due for years ended June 2026 Companies with no chargeable income for the year Confirmed

The full calendar →

Subscribe

Every issue, in your inbox

Every two weeks: the contents of the issue and the opening of the cover story, with a link to read it in full. Free. Unsubscribe in one click.