The review of where business is established, licensed and banked. Subscribe
Jurisdicta
The review of where business is established, licensed and banked.
Issue 001Sunday 11 October 2026
Issue 001 · Sunday 11 October 2026

UAE e-invoicing goes live on 1 January: what changed in October, and what did not

Businesses have until 30 October to appoint a service provider. The go-live date for the largest of them sits where it was. What the Ministry of Finance has done instead is remove two rules that shaped how groups built their finance function.

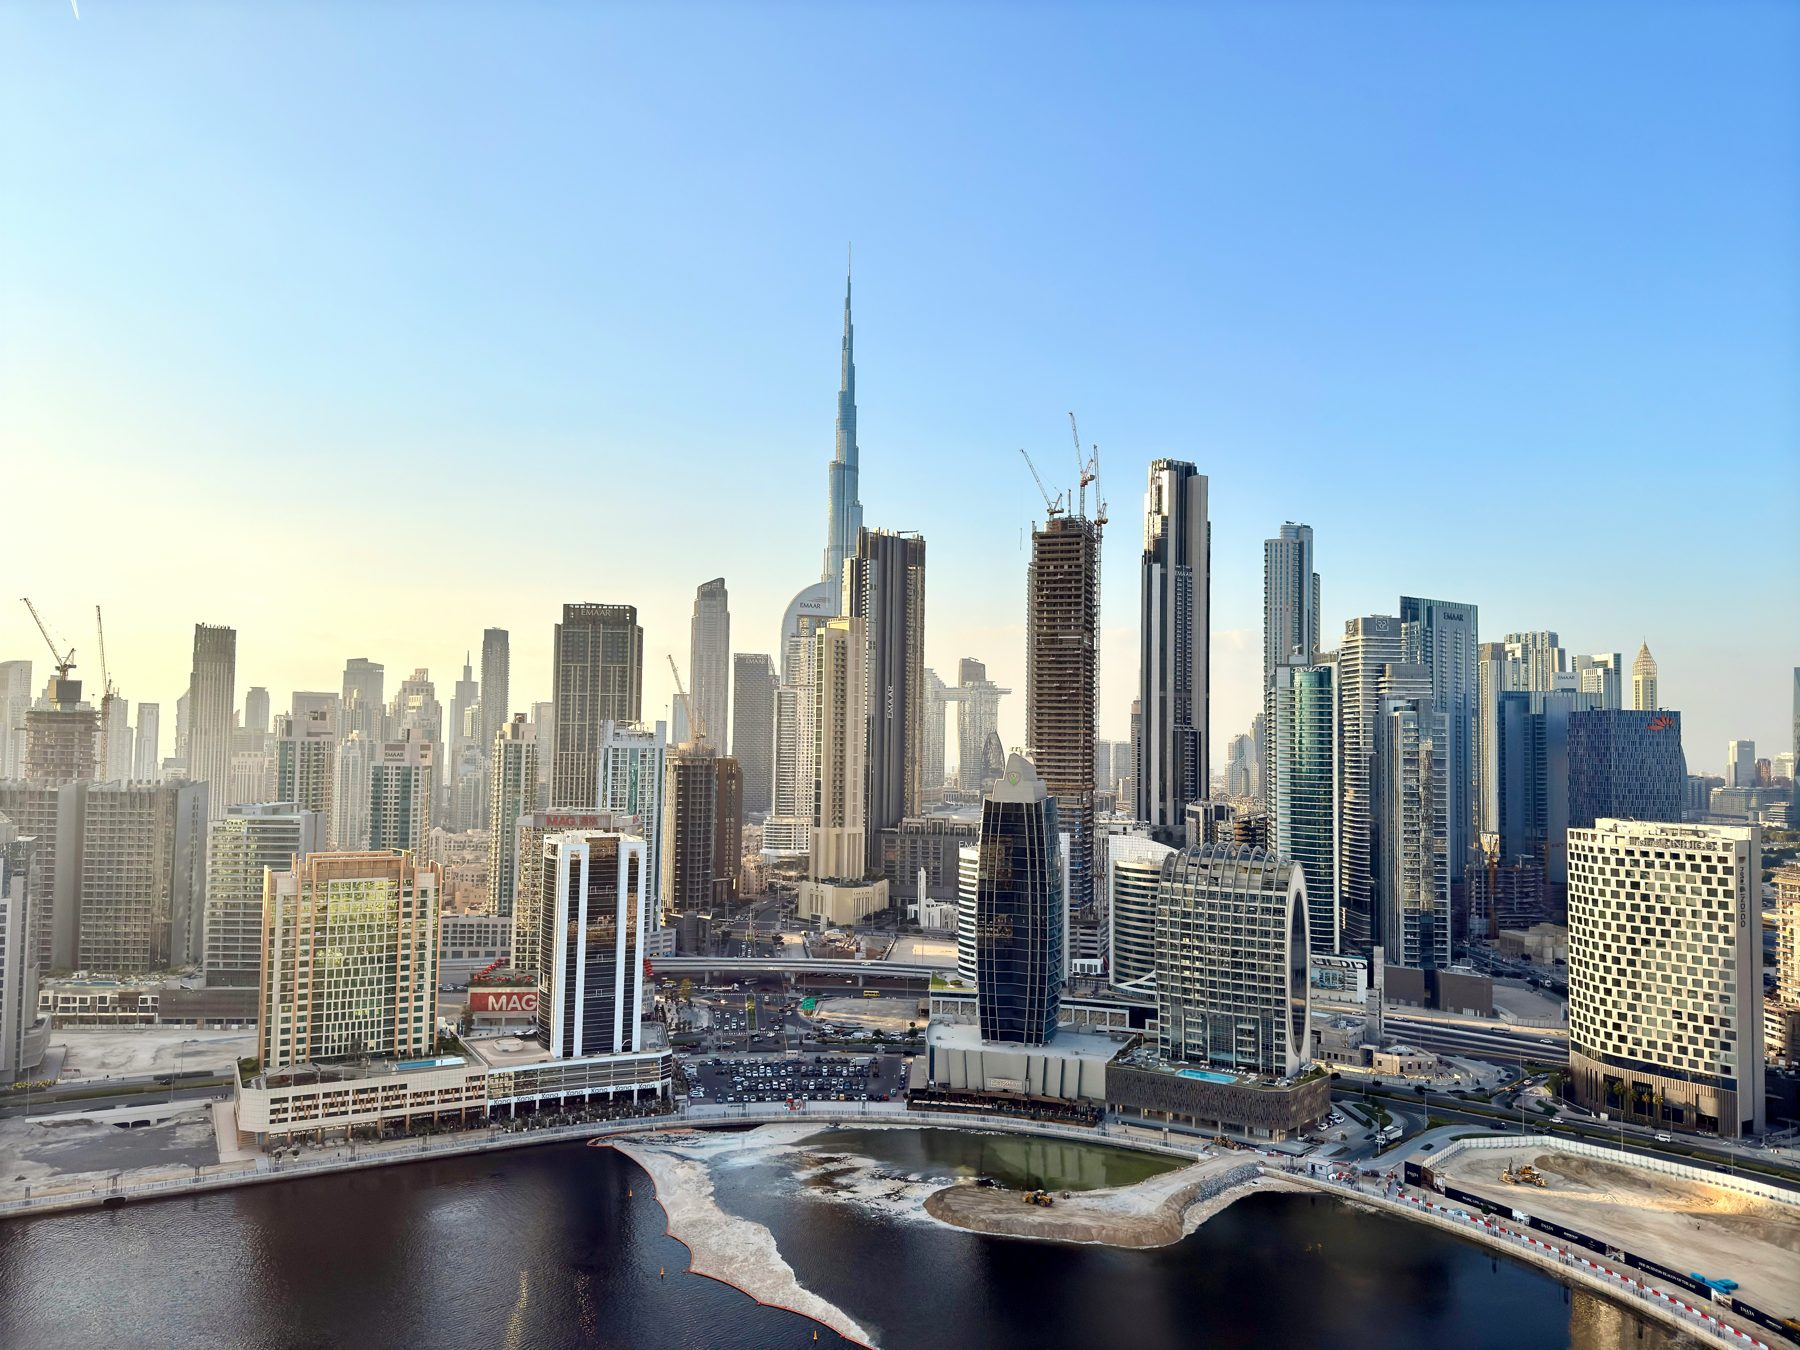
Dubai skyline in Business Bay with the Burj Khalifa
Photo: Sirav Talwar / Unsplash

01

Cover story

United Arab Emirates

On 1 January 2027 electronic invoicing becomes mandatory in the UAE for its largest businesses. Under Article 5 of Ministerial Decision No. 244 of 2025, any business with annual revenue of AED 50 million or more must have the system in place by that date. Those businesses were first told to appoint an Accredited Service Provider by 31 July 2026. In May the Ministry moved that date to 30 October 2026. It is under three weeks away.

Go-live is under three months off, and in that same stretch the Ministry of Finance has been rewriting the rules themselves. Ministerial Decision No. 197 of 2026, which amends Ministerial Decision No. 243 of 2025 on the e-invoicing system, took effect from 1 October 2026. We read it with one question in mind: what does it change about how a group organises itself? Three of its changes bear on exactly that.

Read the cover story

02

The Economy

United Arab Emirates

The UAE in the first half of 2026: a slower economy with a faster financial sector

Real GDP barely moved over the half year, and the second quarter did the damage. Finance, technology and health kept expanding, and the non-oil share of the economy rose again.

Real growth by activity, UAE, first half 2026 (year on year)

Read The Economy

03

The Rulebook

6 items

UAE extends Small Business Relief to tax periods ending on or before 31 December 2029

Small Business Relief for corporate tax now runs to tax periods ending on or before 31 December 2029 (Ministerial Decision No. 131 of 2026, announced on 7 August 2026). If you are a resident business with revenue of up to AED 3 million, you can keep electing for it until then.

What to do: Small resident businesses should test revenue against the AED 3 million limit for every tax period and make the election in each corporate tax return. Check eligibility again before each return deadline, not once.

Our readingThree years of certainty for genuine small businesses is welcome. It is no reason to split a business into several companies, which is exactly what Article 6 of the 2023 decision is there to catch.

Read the full article · 3 min →

Pillar Two in the UAE: registration deadlines set, information return rules in force

The Pillar Two Information Return rules are in force (Ministerial Decision No. 133 of 2026, issued on 3 August 2026, effective on issue) and apply to fiscal years starting on or after 1 January 2025. The Federal Tax Authority has also published a guide on scope and registration for the Domestic Minimum Top-up Tax, which applies to multinational groups with annual revenue of EUR 750 million or more. Registration is due within seven months of the end of the first in-scope fiscal year (FTA Decision No. 12 of 2026). For fiscal years ending before 30 April 2026 the transitional deadline is 30 November 2026. Register late and it costs AED 10,000.

What to do: If your UAE entity belongs to a group with EUR 750 million or more in revenue, confirm its first in-scope fiscal year now and register, or have a Domestic Designated Filing Entity register for it, within seven months of the end of that year. For fiscal years ending before 30 April 2026 the deadline is 30 November 2026.

Our readingThe UAE minimum tax is now an administrative regime as well as a rate. In the first year, a missed registration or notification is a likelier problem than the tax itself.

Read the full article · 5 min →

UAE banks must give SMEs a Key Facts Statement and 60 days' notice of changes

Banks and finance companies serving small and medium-sized enterprises must now provide a Key Facts Statement and give 60 days' notice before changing terms or fees (the Central Bank's SME Customer Protection Regulation, Circular C 2/2026, in force from 13 September 2026).

What to do: Before signing for any new account or facility, ask for the Key Facts Statement and the fee schedule. Check that any change to a fee or term took effect at least 60 days after written notice; if it did not, complain to the bank first and then to Sanadak.

Our readingA small but real improvement for SMEs, whose banking costs in the UAE have often changed with little warning. It deals with price and process, not with access to an account.

Read the full article · 3 min →

Management services to global business entities move from zero-rated to VAT-exempt

From 1 October 2026, services that management licence holders supply to Global Business Licence holders are exempt supplies under item 97 of the First Schedule to the VAT Act, and so are their services to qualifying trusts and foundations, meaning those whose settlor or founder and most beneficiaries are non-resident. The Mauritius Revenue Authority set this out in a communiqué of 2 October 2026. Until then the same services were zero-rated.

What to do: Management companies should identify which customers fall within item 97, recalculate recoverable input VAT from 1 October 2026 and review pricing before the 2027 fee letters go out. Global Business Companies should expect their administrators either to raise fees or to explain why they are not.

Our readingRemoving zero-rating turns VAT that administrators could recover into a cost they carry. Part of it is likely to reach administration fees in 2027.

Read the full article · 4 min →

FSC stops accepting applications for Managed Corporate Service Providers

The Financial Services Commission's Circular Letter CL20260309 of 8 September 2026 suspends the Managed Corporate Service Provider (MCSP) policy with immediate effect and revokes the 2005 Practice Notes on which it rested. The FSC will no longer receive or process new applications for management company licences structured as MCSPs. Existing MCSPs that have passed their three-year limit have a transition period of up to one year in which to convert to a full Management Company licence.

What to do: Clients whose administrator operates as an MCSP should ask now for its conversion plan and timetable. MCSPs past three years must apply to convert within one year of 8 September 2026.

Our readingThe FSC is concentrating administration in fully licensed firms with real local substance. The likely result is fewer administrators, each of them larger.

Read the full article · 3 min →

FSA reminds IBCs that incorporation is not a licence

Circular No. 5 of 2026 from the Financial Services Authority (FSA), issued on 14 August 2026, reminds International Business Companies (IBCs) of the restrictions in section 5 of the IBC Act 2016. Incorporation or continued registration under the Act "does not constitute or substitute any licence". An IBC that carries on regulated activity abroad must state which authority licenses it on its website, in its client agreements and in its marketing material. Fines reach USD 50,000, with higher amounts for certain breaches of the VASP Act.

What to do: Review now every Seychelles IBC in the group that deals with clients. Confirm that each holds the licence its activity needs and displays the licensing authority on its website, client agreements and marketing, or stop the activity. The FSA expects corrective action immediately.

Our readingThe circular is a warning shot. Regulated activity through an unlicensed IBC, or vague wording that suggests FSA approval, is now a visible enforcement risk rather than a technicality.

Read the full article · 3 min →

04

The Structure

Illustrative

A Mauritius holding company over a UAE free zone business

One of the most common set-ups for founders who operate from the UAE and invest across Africa and Asia. It works only with the governance to hold it up.

100%Administers100%BankedFoundersShareholdersMAURITIUSHolding companyGlobal Business CompanyMAURITIUSManagement companyFSC management licenceUAEOperating companyFree zone companyMAURITIUSPrincipal bank accountHolding company account
Illustrative structure. Not a client engagement and not advice for any particular case.

Why each piece sits where it does

05

Immigration by Investment

2 features
06

Wealth and Succession

1 feature
07

Field Notes

On the ground

Three ADGM consultations close in November

Abu Dhabi Global Market has three public consultations open. Two of them close on Friday 6 November.

Fees and general rulebooks (FSRA CP 6/2026). The FSRA proposes revisions to its Fees and General Rulebooks. Comments close on 6 November. If you run an authorised firm and are building the 2027 budget, read the fee proposals before the window shuts.

Business centres (Registration Authority CP 7/2026). The Registration Authority proposes a regulatory framework for business centres in ADGM. Comments close on 6 November. It reaches two groups: the operators of serviced offices, and the companies that use those offices as their registered address.

DeFi risk management (FSRA CP 5/2026). The FSRA proposes guidance on risk management for decentralised finance. This one runs longer: comments close on 30 November.

A consultation is the cheapest point at which to shape a rule. Smaller firms' responses do get read, and they are often the only evidence a regulator has of how a proposal lands outside the largest institutions.

08

By the Numbers

USD 2,600
Annual FSC fee for a Mauritius Global Business Company, from 1 July 2026
The FSC's revised fee schedule, in operation from 1 July 2026 under Government Notice No. 119 of 2026. Pay three to six months late and a Global Business Company owes double, USD 5,200. The figure is the licence fee alone; administration and audit are billed separately.
09

Jurisdiction Profile

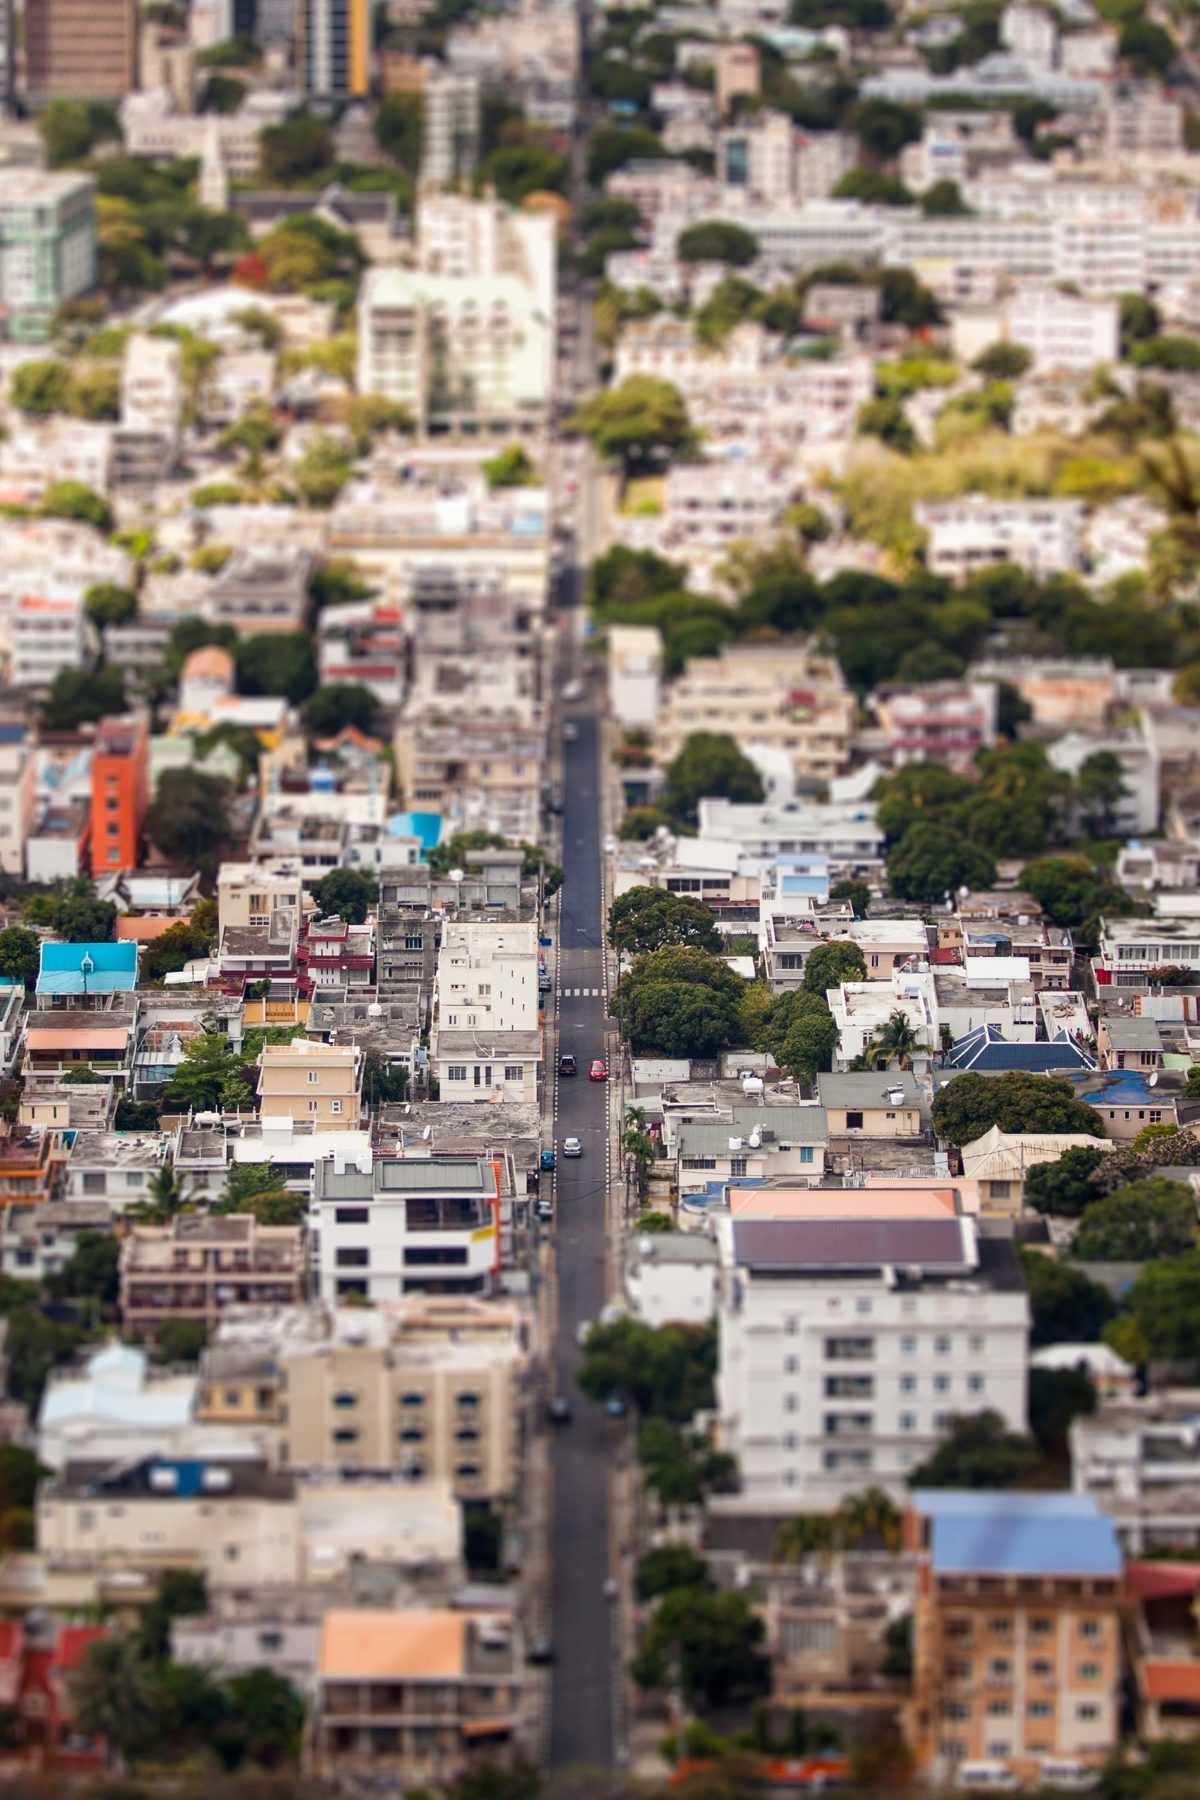
Aerial view of Port Louis, Mauritius
Photo: Fabien TWB / Unsplash
Mauritius

Mauritius: the regulated gateway between Africa, Asia and the Gulf

What it is used for. Holding companies, funds, family offices and treasury companies, above all for investment into Africa and India. The groups that choose it want a regulated jurisdiction built on substance, and have decided against a pure registry.

The regulator. The Financial Services Commission (FSC) licenses global business under section 71 of the Financial Services Act 2007. Tax sits with the Mauritius Revenue Authority.

The main vehicles. The Global Business Company (GBC), managed and controlled from Mauritius; the Authorised Company, majority owned by non-citizens and managed and controlled outside Mauritius; and trusts, foundations and limited partnerships.

What substance means. There are three tests, and each asks whether the company is genuinely run from the island: a GBC must carry out its core income-generating activities in or from Mauritius, be managed and controlled from Mauritius and be administered by a licensed management company. In weighing them, the FSC considers whether it has at least two resident directors and its principal bank account in Mauritius.

Tax. Corporate tax is 15 per cent. Foreign dividends, interest and certain other income can qualify for a partial exemption of 80 or 95 per cent, provided the company meets conditions on core activities, staff and expenditure in Mauritius. Groups with revenue of EUR 750 million or more also face a 15 per cent Qualified Domestic Minimum Top-up Tax.

What it costs. From 1 July 2026 the FSC annual fee is USD 2,600 for a GBC and USD 1,400 for an Authorised Company, due each 1 July. Administration, audit and directors' fees come on top.

Reporting. A GBC files audited financial statements with the FSC within six months of its year end. Its tax return is due within six months of the end of the month in which that year ends.

What to watch. Beneficial ownership registers must record each owner's date of birth by 30 June 2027. Management services to global business entities became VAT-exempt on 1 October 2026. The FSC has suspended the Managed Corporate Service Provider model. And Mauritius still sits in ESAAMLG enhanced follow-up, with its next mutual evaluation approaching.
Our readingThe right answer when a holding company needs real governance and a regulator that counterparties recognise, with a treaty network behind both. If the aim is the lowest cost or the least paperwork, choose somewhere else.

Everything we have published on Mauritius →

10

The Diary

Next 90 days
DateJurisdictionWhat falls dueWho it affectsStatus
6 November 2026 ADGM Consultations close on the FSRA fees and general rulebook revisions (CP 6/2026) and a framework for business centres (CP 7/2026) ADGM firms and business-centre operators wishing to comment Confirmed
16 November 2026 United Arab Emirates Excise tax return and payment due Excise tax registrants Confirmed
16 November 2026 Hong Kong Profits tax returns for 2025/26 due, accounting date code M (year ends 1 January to 31 March 2026), under the block extension scheme Companies filing through tax representatives Confirmed
30 November 2026 Singapore Form C-S, Form C-S (Lite) and Form C due for Year of Assessment 2026 Companies tax resident or operating in Singapore Confirmed
30 November 2026 Mauritius Corporate tax return and tax due for years ended May 2026; advance payment statement for the quarter to 31 August 2026 Companies, including Global Business Companies Confirmed
30 November 2026 United Arab Emirates Corporate tax return and payment due for tax periods ended 28 February 2026 (nine months after the period end) Corporate tax registrants with a February year end Confirmed
30 November 2026 ADGM Consultation closes on FSRA guidance on DeFi risk management (CP 5/2026) Virtual asset and DeFi firms in or entering ADGM Confirmed
30 November 2026 United Arab Emirates Top-up Tax registration deadline for in-scope entities whose fiscal year ended before 30 April 2026 (FTA Decision No. 12 of 2026, Art. 2(2)); AED 10,000 penalty for late registration UAE entities of multinational groups with EUR 750 million or more in revenue, or their Domestic Designated Filing Entity Confirmed
29 December 2026 Mauritius Corporate tax return and tax due for years ended June 2026; advance payment statement for the quarter to 30 September 2026 Companies, including Global Business Companies Confirmed
31 December 2026 Seychelles Register of directors must record the nominee status of any director and the nominator's details International Business Companies Confirmed
31 December 2026 Mauritius Audited financial statements due to the FSC for licensees with a June 2026 year end (six months after the year end) Global Business Companies and other FSC licensees Confirmed
31 December 2026 United Arab Emirates Corporate tax return and payment due for tax periods ended 31 March 2026 Corporate tax registrants with a March year end Confirmed
1 January 2027 United Arab Emirates E-invoicing becomes mandatory for businesses with annual revenue of AED 50 million or more VAT and corporate taxpayers above the threshold Confirmed
1 January 2027 Seychelles Filings must carry the names and appointment dates of a company's current directors International Business Companies and their registered agents Confirmed
1 January 2027 Singapore Crypto-Asset Reporting Framework regulations enter into force; reporting service providers begin collecting data Crypto-asset service providers with a Singapore nexus Confirmed
1 January 2027 DIFC Revised conflict-of-interest rules for credit rating agencies apply DFSA-authorised credit rating agencies Confirmed
1 January 2027 United Arab Emirates One-year period for firms to bring their status into line with the new Capital Market Authority law ends, unless extended by the CMA Board Firms carrying on financial or virtual asset activities within the CMA's scope To confirm

The full calendar →

Subscribe

Every issue, in your inbox

Every two weeks: the contents of the issue and the opening of the cover story, with a link to read it in full. Free. Unsubscribe in one click.